The Power Inversion: Inside XPeng’s 50,000 Surge and Li Auto’s Sudden Squeeze
October delivery figures reveal a dramatic realignment among China’s EV vanguard as XPeng hits a milestone ceiling and Li Auto stumbles.
In a domestic market crowded with more than 100 homegrown carmakers—from colossal conglomerates like BYD, Geely, and Changan to hyper-agile disruptors like Xiaomi and AITO—the monthly delivery scorecard is more than a sales metric; it is an unforgiving real-time referendum. The freshly released October 2026 delivery numbers have dropped, and the established hierarchy among China’s original startup triumvirate has undergone a violent tectonic shift.
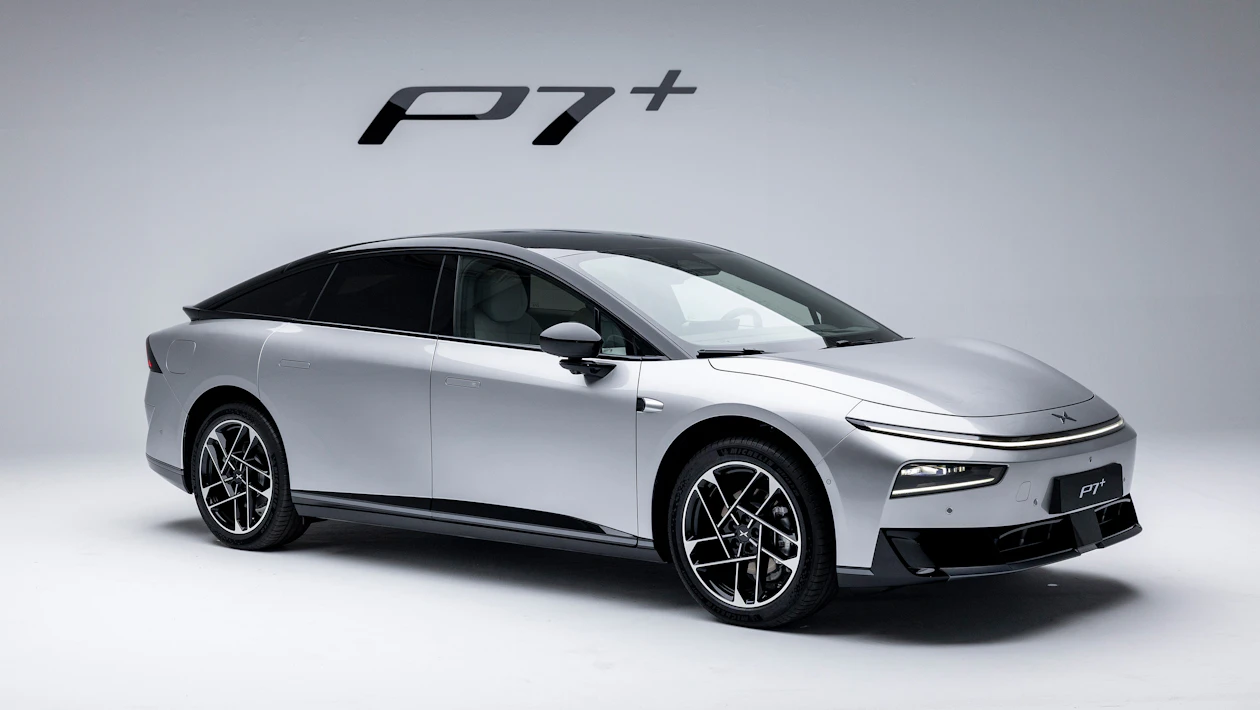
The headline breakthrough belongs to XPeng, which pushed past the coveted 50,000-delivery threshold in a single month for the first time in its corporate history. After quarters spent refining its smart-driving architecture and aggressive pricing strategy, the Guangzhou-based automaker registered a blistering year-on-year surge, with initial reports clocking over 42,000 to 50,000 units delivered—representing a massive 76 percent climb over twelve months and cementing its status as an undisputed volume powerhouse.
Nio mirrored that aggressive trajectory, posting 40,397 deliveries in October to notch a staggering 93 percent year-on-year leap. The performance represents tangible validation for Nio’s protracted capital investments into dual-brand retail footprints and expansive battery-swap infrastructure, proving that premium positioning can successfully scale when execution aligns with aggressive product cadence.
The bitter contrast belongs entirely to Li Auto. Long regarded as the undisputed cash-flow king and volume anchor among China's pure-play EV pioneers, Li Auto saw its monthly output slip sharply to 29,025 deliveries. The dip marks a vulnerable plateau for the brand as competitors encroach on its once-exclusive extended-range SUV heartland and newly minted pure-electric entries fragment family buyers across Tier 1 and Tier 2 cities.The bitter contrast belongs entirely to Li Auto. Long regarded as the undisputed cash-flow king and volume anchor among China's pure-play EV pioneers, Li Auto saw its monthly output slip sharply to 29,025 deliveries. The dip marks a vulnerable plateau for the brand as competitors encroach on its once-exclusive extended-range SUV heartland and newly minted pure-electric entries fragment family buyers across Tier 1 and Tier 2 cities.
This reshuffle unfolds beneath the towering shadow of broader industrial scale. Mainstream premium players like Geely’s Zeekr demonstrated relentless expansion, posting 222,123 deliveries across its expanding portfolio—an 87 percent year-on-year jump that highlights how quickly well-capitalised automotive giants can flood the market with platform-shared electric architecture.
The takeaway from October’s balance sheet is clear: early market lead counts for nothing in China’s relentless EV proving ground. The moat built by early hybrid architectures is evaporating, and the spoils are rapidly migrating toward manufacturers delivering uncompromising autonomous software, lightning-fast manufacturing turnaround, and razor-sharp pricing.The takeaway from October’s balance sheet is clear: early market lead counts for nothing in China’s relentless EV proving ground. The moat built by early hybrid architectures is evaporating, and the spoils are rapidly migrating toward manufacturers delivering uncompromising autonomous software, lightning-fast manufacturing turnaround, and razor-sharp pricing.
Gallery
"XPeng pushed past the coveted 50,000-delivery threshold in a single month for the first time in corporate history."
Why it matters
The October delivery inversion marks the end of Li Auto's uncontested volume supremacy among China's EV startups. With XPeng and Nio achieving near-triple-digit growth, the battle for domestic scale is moving from niche luxury segments into uncompromising mass-volume software warfare.
Sources
- 1.
- 2.
- 3.
- 4.
Reported by the Downforce & Divots desk from the sources above.
The clubhouse.
- No replies yet. Be the first.